
Key takeaways
- The appraisal clause in an auto policy settles disagreements over the amount of loss, such as repair cost or actual cash value. It does not decide coverage or who caused the crash.
- You start it with a written demand that names your appraiser. Some policies set a deadline, such as 60 days after proof of loss, so read yours before you wait.
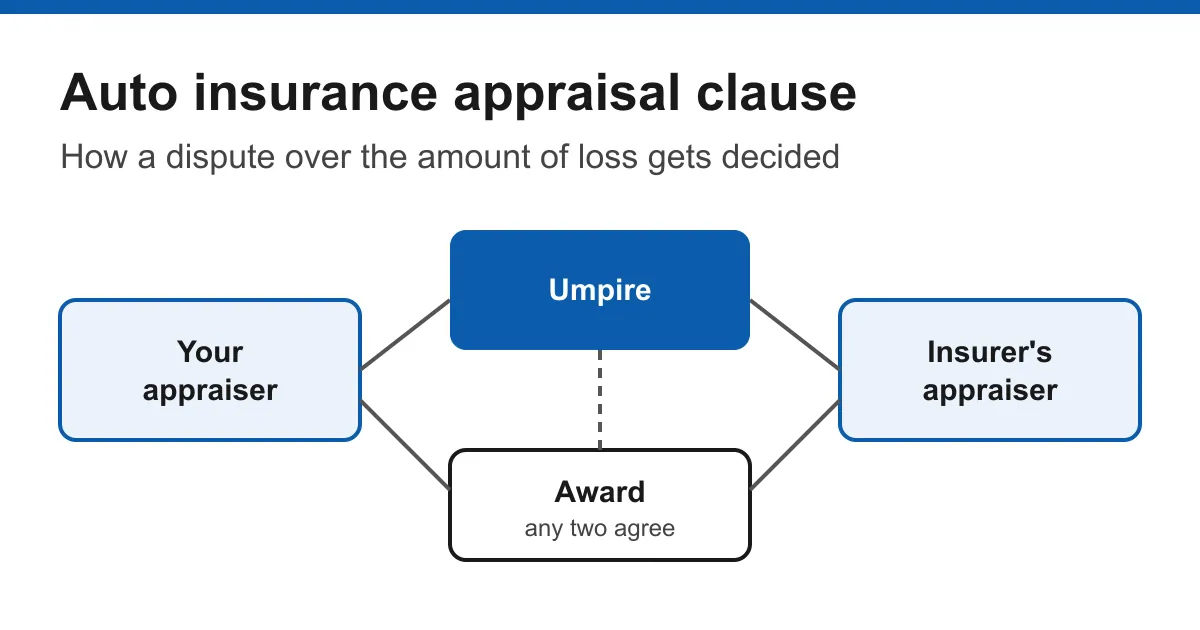
- Each side hires its own appraiser, who must be competent and disinterested (some forms say impartial). The two appraisers choose an umpire.
- Under the standard wording, each side pays its own appraiser. Some states, Oregon among them, shift appraisal costs to the insurer in some cases.
- When any two of the three (two appraisers and the umpire) sign the same figure, that award sets the amount of loss.
The appraisal clause in auto insurance is a policy condition that lets you or your insurer call in outside appraisers when you can't agree on the amount of loss. Each side hires an appraiser, the two appraisers choose an umpire, and a figure signed by any two of the three becomes the amount the claim is paid on. You start it with a written demand.
Below, we go through the clause line by line in plain English: how to invoke it, who can be your appraiser, what the umpire does, who pays, and what an appraisal can't decide. Policies and state rules differ, so where this guide and your policy disagree, your policy wins.
What is the appraisal clause in auto insurance?
The appraisal clause is a short paragraph, usually titled "Appraisal," in the physical damage part of your auto policy (often Part D, Coverage for Damage to Your Auto). It applies to first-party claims, meaning claims under your own collision or comprehensive coverage. You can't use it against the other driver's insurer, because you aren't a party to that policy.
The standard ISO-style wording that many carriers start from says roughly this:
- If you and the insurer don't agree on the amount of loss, either side can demand an appraisal.
- Each side picks a competent and impartial appraiser.
- The two appraisers pick an umpire.
- The appraisers each state the actual cash value and the amount of loss.
- If they don't agree, they send their differences to the umpire.
- A decision agreed to by any two of the three is binding.
- Each side pays its own appraiser, and the policy says how other appraisal costs are shared.
- The insurer doesn't give up any of its rights under the policy by agreeing to appraisal.
Not every appraisal clause auto insurance companies write follows this template. Some say "disinterested" instead of "impartial." Some add a deadline for the demand. Some word appraisal as an option both sides must agree to, rather than a right either side can demand, and trade groups have reported carriers narrowing the clause to total-loss values only. Pull your full policy (the booklet plus any state amendment endorsements, not just the declarations page) and find the exact paragraph before you do anything else.
If you can't find one at all, read what to do when your policy has no appraisal clause.
When does it make sense to use the appraisal clause?
The appraisal clause makes sense when the insurer agrees the loss is covered but you disagree about the money. Typical examples:
- The repair estimate leaves out parts, labor operations or calibration the car needs.
- The actual cash value on a totaled car is built on poor comparables or heavy condition deductions.
- The two sides are a few thousand dollars apart and the adjuster has stopped moving.
It is a poor fit when the insurer denies coverage, blames you for the crash, or says an exclusion applies. Those are coverage and liability fights, and appraisal doesn't reach them (more on that below).
Run the numbers before you start. If the gap between the offer and a supportable value is $400, your share of the appraisal costs could eat most of it. If the gap is $4,000, appraisal often costs far less than the difference. An independent appraisal of your own first tells you whether the gap is real.
How do you invoke the appraisal clause?
You invoke the appraisal clause by sending your insurer a written demand for appraisal under the policy. A phone call to the adjuster doesn't count. Here's the sequence most auto appraisals follow.
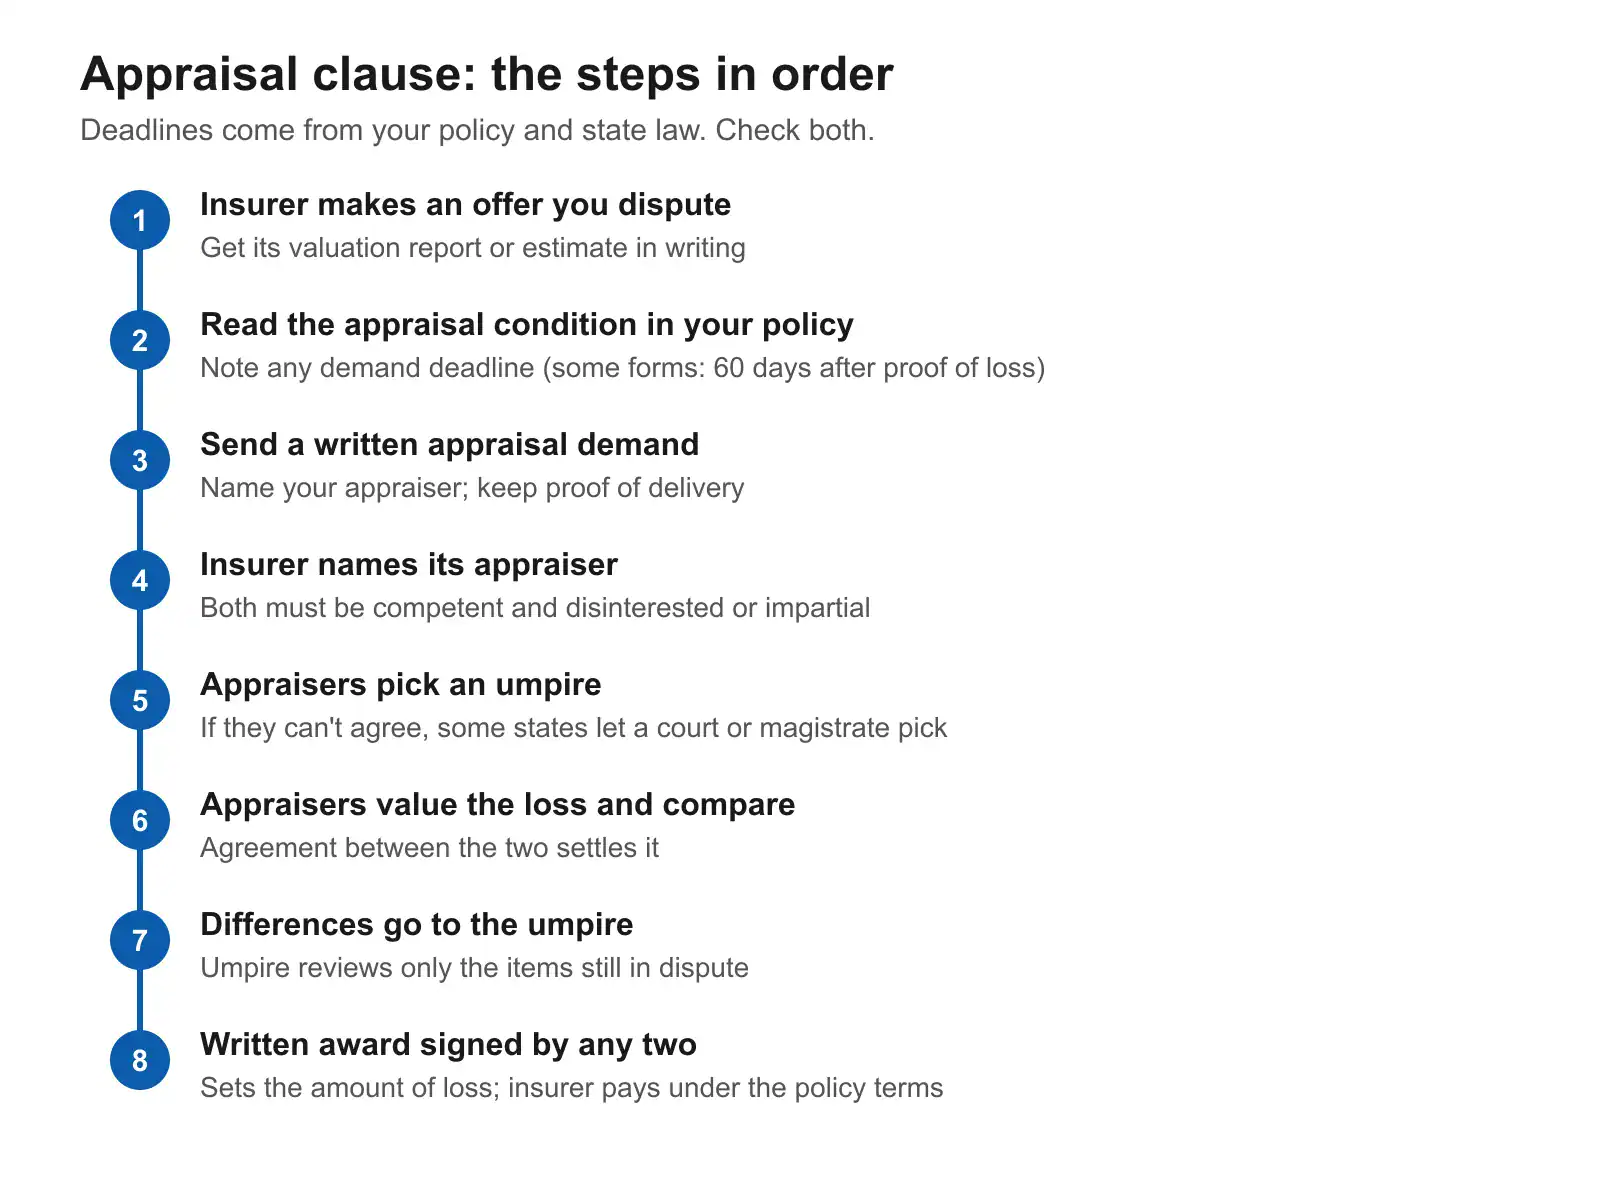
- Get the insurer's position in writing: the valuation report or repair estimate the offer is based on.
- Read your appraisal condition. Note who can demand appraisal, any deadline, and how costs are split.
- Line up your appraiser. Confirm they're independent, licensed where your state requires it, and paid in a way that doesn't depend on the result.
- Send the written demand. Email plus certified mail gives you a clean record.
- Wait for the insurer to name its appraiser. Some forms and state laws set a window for this. If yours doesn't, ask for a name by a specific date.
- The two appraisers choose an umpire, ideally early, before either has finished a valuation.
- The appraisers value the loss and compare. If they agree, they sign, and that's the award.
- Anything they can't agree on goes to the umpire. An award signed by any two of the three sets the amount of loss.
How long do you have to demand appraisal?
Some auto policies give you a deadline, and the one we see most is 60 days after you file proof of loss. Georgia's Court of Appeals treated a 60-day appraisal demand window as a condition the policyholder had to meet in Williams v. Southern General Insurance Co. (1994). Other policies have no stated deadline at all, and a few states regulate the timing themselves.
So don't wait for the adjuster's "final" offer if the clock is already running. If your policy ties the deadline to proof of loss, find out from the adjuster in writing whether and when your proof of loss was received.
What should a written appraisal demand include?
A written appraisal demand should identify the claim, say plainly that you are demanding appraisal under the policy, state what is in dispute, and name your appraiser. It doesn't need legal language. Use this checklist:
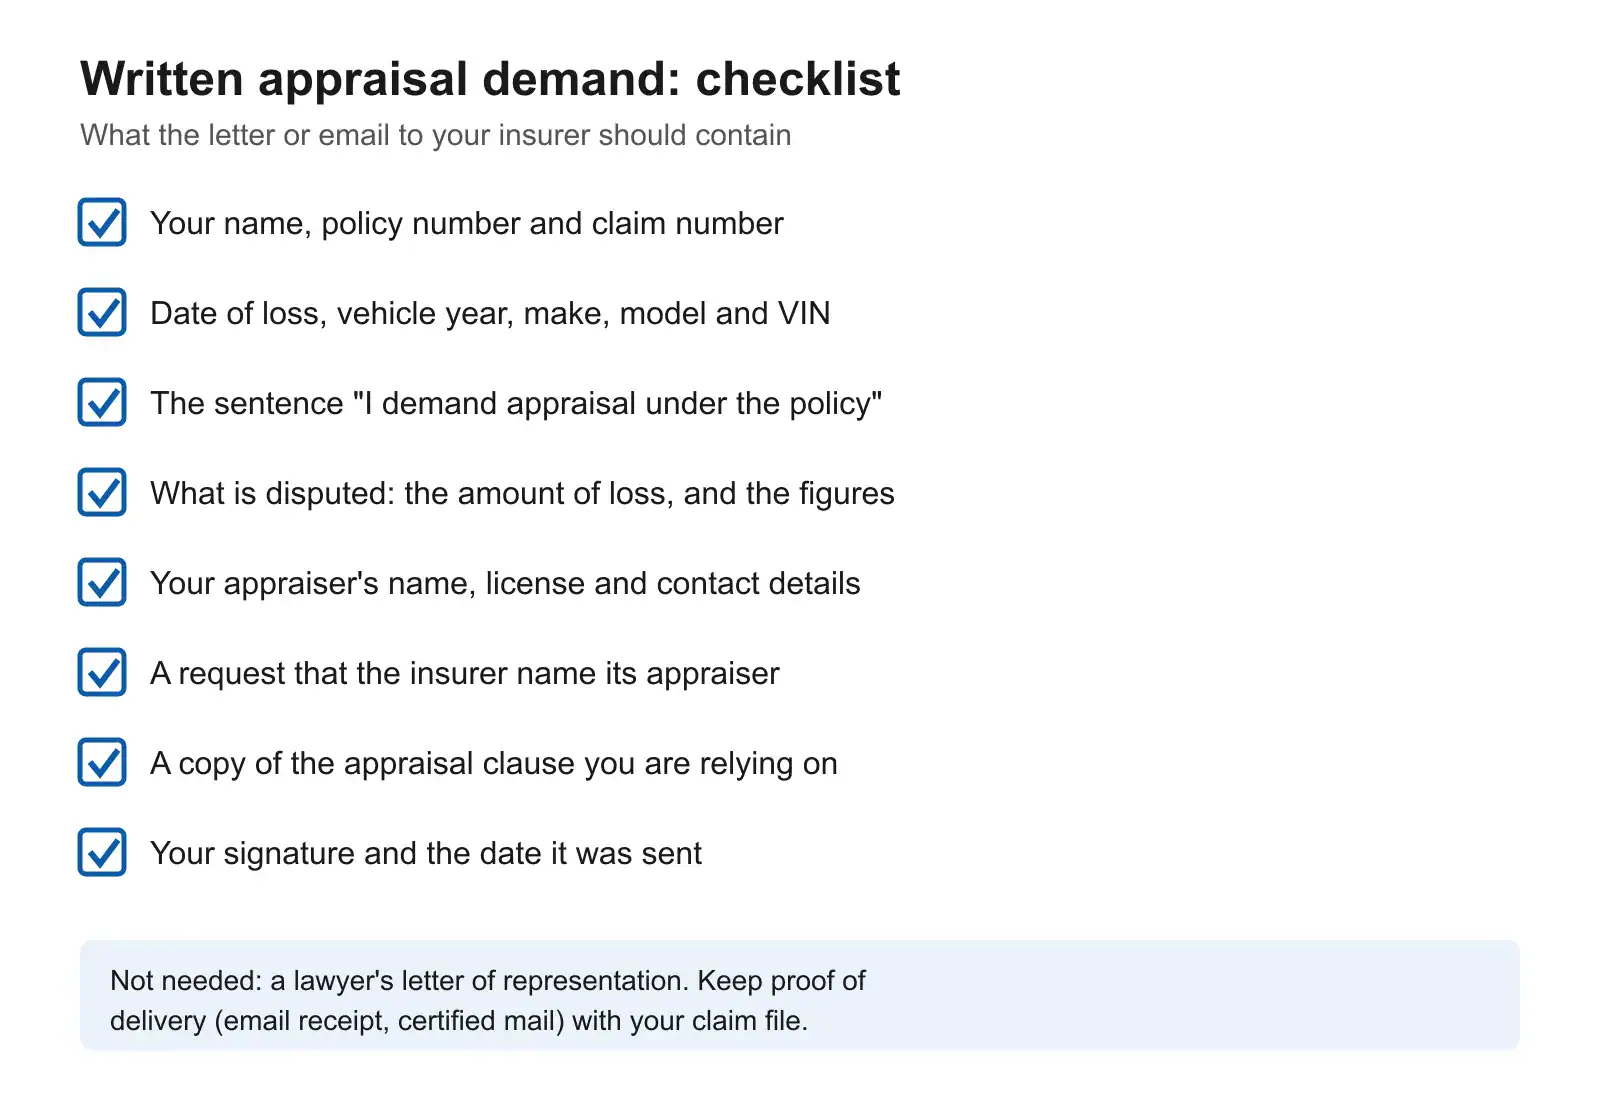
- Your name, policy number and claim number
- Date of loss, and the vehicle's year, make, model and VIN
- A direct sentence such as "I am demanding appraisal under the Appraisal provision of my policy"
- What's disputed: the amount of loss, with the insurer's figure and your figure
- Your appraiser's name, license number (if your state licenses appraisers) and contact details
- A request that the insurer name its appraiser by a specific date
- A copy of the appraisal paragraph from your policy
- Your signature and the date sent
Keep the email receipt or certified-mail tracking with your claim file. If there's ever an argument about whether you met a deadline, that record settles it.
Do you need a letter of representation?
No. A letter of representation is something a lawyer sends to tell an insurer the lawyer now represents you. The appraisal clause doesn't mention one, and your appraiser isn't your lawyer. Some adjusters ask for it anyway, which stalls the process. We cover how to answer that request in letter of representation vs. the appraisal clause.
Can you choose your own appraiser?
Yes, you choose your own appraiser under the appraisal clause, and the insurer chooses its own. The limit is the word in the policy: "competent" plus "disinterested" or "impartial." In practice that means someone who knows how to value vehicles and has no stake in your claim.
People who usually don't qualify:
- You, your spouse or a relative
- Your lienholder or leasing company
- The body shop that will be paid from the settlement
- Anyone whose fee rises or falls with the appraised value
The last one matters most. An appraiser paid a percentage of the award has a reason to push the number up, and the insurer can use that to challenge the appraiser or the award. Courts in different states have handled fee arrangements differently, so check how yours treats it. Appraisal Engine charges a flat fee for the appraisal itself; how the separate settlement fee works, and why a cap is not a contingency, is explained in contingency fees and the appraisal clause.
Some states also license vehicle appraisers. Oregon's statute, for example, expects the appraiser in a motor vehicle appraisal to be "competent and disinterested" and to hold an Oregon vehicle appraiser certificate or an equivalent license from another state (ORS 742.466).
What does the umpire in an insurance appraisal do?
The umpire in an insurance appraisal is a neutral third person who decides only the items the two appraisers can't agree on. The umpire isn't hired by either side alone. The appraisers choose the umpire together, ideally at the start, so the choice isn't colored by how far apart their numbers turn out to be.
The umpire normally reviews both appraisers' reports, the photos and estimates, and any comparables. The umpire may inspect the car. Then the umpire signs a figure with whichever appraiser it agrees with, or works out a number that one appraiser will sign. Two signatures make an award.
What if the appraisers can't agree on an umpire? Many policies say a judge can appoint one on request. Some states write the rule into law. North Carolina's statute lets a magistrate or clerk of court pick the umpire if the appraisers haven't agreed within 15 days (N.C. Gen. Stat. § 20-279.21(d)(1)).
Appraisal Engine also offers umpire services in first-party appraisal-clause disputes, so we've worked these files from the neutral seat as well as for policyholders.
Who pays for appraisal?
Under the standard wording, you pay your appraiser and the insurer pays its appraiser. Some state laws change that.
| Cost | Standard ISO-style clause | Example state change |
|---|---|---|
| Your appraiser | You pay | Oregon: insurer reimburses your reasonable appraisal costs if the final appraisal beats its last offer (ORS 742.466) |
| Insurer's appraiser | Insurer pays | Insurer pays |
| Other appraisal costs | Set by your policy | Check your state |
Your appraiser's fee depends on who you hire and what the car needs. At Appraisal Engine, the desk appraisal is a flat $275 and a field appraisal with inspection is $425; see appraisal pricing. Working the claim through the clause (talking with the other appraiser, agreeing on an umpire, closing out the award) is a separate, optional appraisal clause settlement service billed at $300 an hour and capped at 25% of the increase over the insurer's offer.
Not sure the gap is worth it? Send your repair estimate or valuation for a free claim review. If the carrier already paid you fairly, we'll say so.
What does an auto insurance appraisal look like in practice?
An auto insurance appraisal usually narrows a dispute to a handful of line items before the umpire ever gets involved. Here is an illustrative example (the numbers are made up to show the mechanics, not taken from a real file):
| Stage | Repair figure |
|---|---|
| Insurer's estimate | $14,200 |
| Your appraiser's estimate | $17,900 |
| Insurer's appraiser after reviewing both | $15,800 |
| Items still disputed | OEM bumper reinforcement, ADAS camera calibration |
| Umpire signs with your appraiser | $16,950 |
In this example the two appraisers agree on most of the estimate, labor rates and paint included. They split on two items: whether the bumper reinforcement must be an original-equipment part, and whether the camera needs calibration after the windshield and bumper work. The umpire reads the repair procedures for both, and sides with your appraiser on the calibration and with the insurer's appraiser on the part. Your appraiser accepts that figure, and the two of them sign $16,950. Two signatures make it the award.
Your own file could land higher, lower or right on the insurer's number. The point of the example is the shape of the process: the umpire rules on specific disagreements, not on the whole claim from scratch.
What can the appraisal clause decide, and what can't it?
The appraisal clause decides the amount of loss and nothing else. It sets a dollar figure: the actual cash value of the car, or the cost to repair covered damage. It does not decide whether the loss is covered, who caused the crash, whether an exclusion applies, or whether the insurer handled your claim in bad faith.
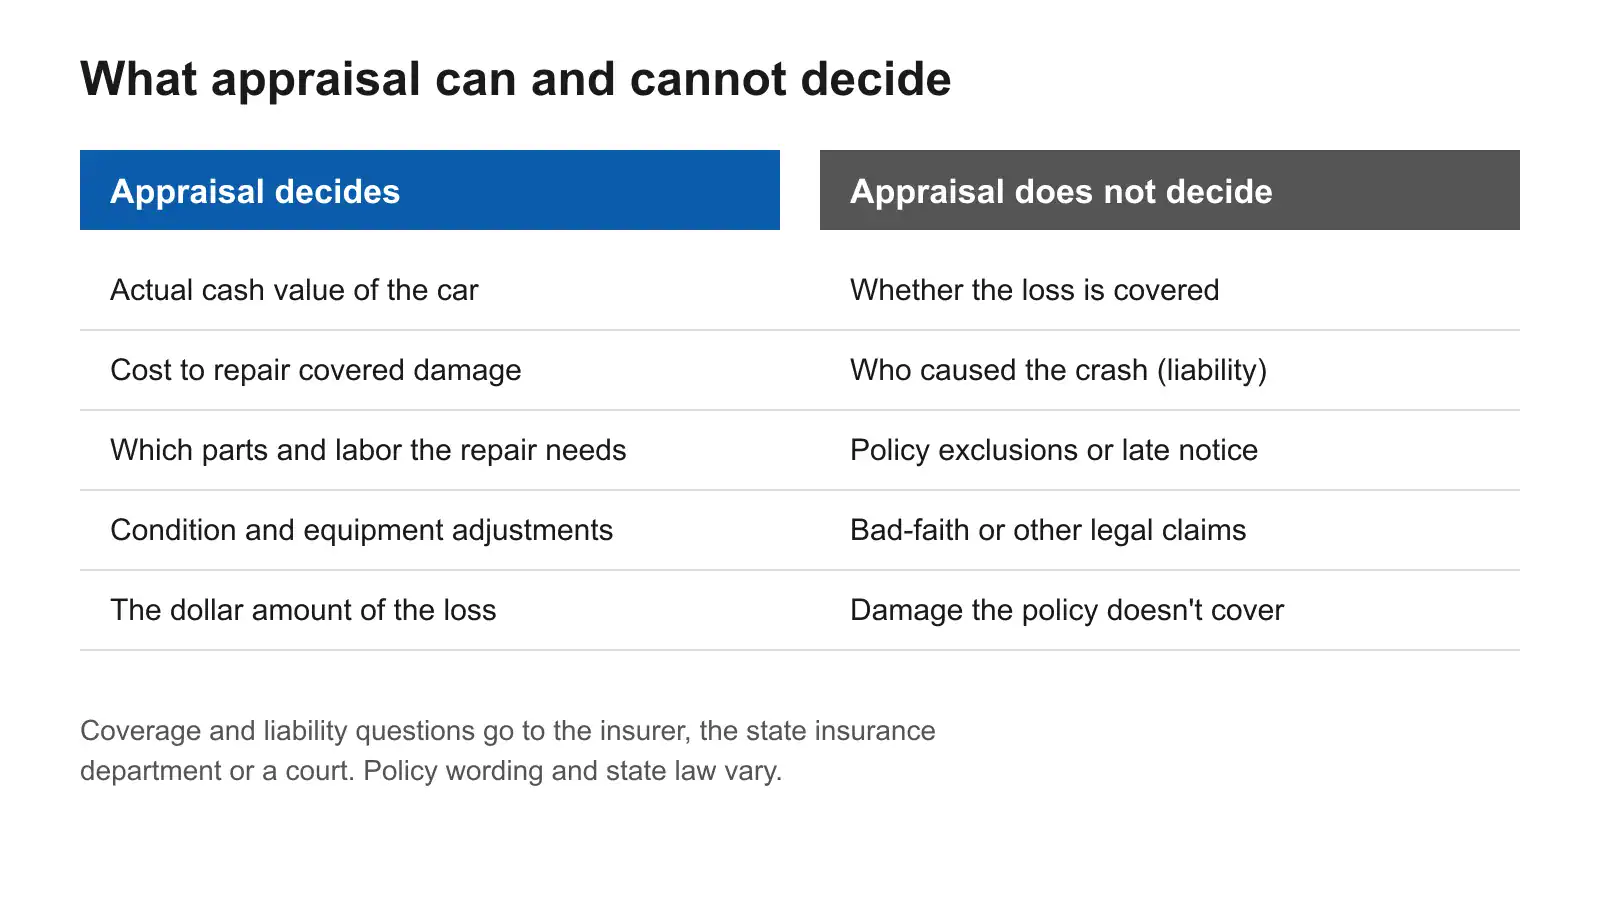
That's why the standard clause ends with the insurer saying it doesn't waive its rights by agreeing to appraisal. Even after an award, the insurer can still argue that part of the damage wasn't caused by the covered accident, or that the policy excludes it. Those fights go to the insurer's internal review, your state insurance department or a court.
The line can blur. Is a damaged sensor part of "the loss" or a separate, unrelated failure? Appraisers and courts sometimes disagree about whether a question like that is about causation (coverage) or about cost (amount). If your dispute mixes both, get the coverage question answered in writing before you spend money on appraisal.
What happens after the award?
Once two of the three sign, the award sets the amount of loss, and the insurer pays under the rest of the policy terms. Your deductible still comes off. On a financed car, the lienholder may be on the check.
An award is hard to overturn. Courts generally set one aside only for things like fraud, a disqualified appraiser or umpire, or an award that strayed into questions it had no power to decide. Disliking the number usually isn't enough. A challenge to the appraiser's qualifications is one of the few that can work, so pick a qualified, disinterested appraiser at the start.
On a total loss, the award fixes the actual cash value, and that number also drives any GAP payout. Total-loss valuation disputes have their own wrinkles, mostly about comparables and condition adjustments, and they're worth a dedicated read before you demand appraisal.
How do state rules change the appraisal clause?
State law can add to the policy, override parts of it, or fill in when it's silent. A few examples of what states regulate:
- Oregon makes the insurer reimburse reasonable appraisal costs when the final appraisal exceeds its last offer (ORS 742.466).
- North Carolina lets a magistrate or clerk pick the umpire after 15 days without agreement.
- Some states license vehicle appraisers, so an unlicensed appraiser's work may not count.
- A few states route certain diminished value disputes through an appraisal process, and the details differ from state to state.
Bills on auto appraisal show up often in state legislatures, so check for changes. Your state's Department of Insurance is the place to confirm the current rule; the NAIC keeps a list of every state insurance department.
Is there a faster route than appraisal?
Sometimes. Many disputes settle after you send the insurer a solid independent appraisal and a demand letter, before anyone invokes the clause. The appraisal clause is the formal backstop: if the adjuster won't move, you have a process that doesn't require a lawsuit. For more on how appraisal fits with diminished value and total loss claims, see our insurance claim FAQ.
Appraisal Engine is an Atlanta-based independent vehicle appraisal company. We prepare USPAP-compliant appraisals nationwide and act as your appraiser or as umpire in auto appraisal-clause disputes. Talk to a licensed appraiser or call (877) 667-2326, Monday to Friday, 8 to 5 Eastern.
This article explains how auto insurance appraisal clauses generally work. It is not legal advice. Appraisal Engine is not a law firm. Your policy wording and your state's law control, and an appraisal does not create coverage or guarantee payment.
Frequently asked questions
What is the appraisal clause in car insurance and how do I invoke it?
The appraisal clause in car insurance is a policy condition that lets you or your insurer ask for an outside valuation when you can't agree on the amount of loss. To use it, send the insurer a written appraisal demand with your claim number, the disputed amount and your appraiser's name. Keep proof that it was delivered.
How long do I have to demand an appraisal under my auto policy?
It depends on your policy and your state. Some auto policies require the demand within 60 days after you file proof of loss. Others give no deadline, and some states set their own timing rules. Read the appraisal condition in your policy, and if it sets a deadline, send your written demand well before it.
Can I choose my own appraiser under the appraisal clause?
Yes. Each side picks its own appraiser, but the policy usually says that appraiser must be competent and disinterested or impartial. You, your relatives and your lienholder generally can't fill the role. Pick a licensed, independent appraiser who has no stake in the claim and whose pay doesn't depend on the final figure.
What happens if the two appraisers cannot agree?
If the two appraisers can't agree on the amount of loss, they send the items still in dispute to the umpire they chose at the start. The umpire reviews both sides' work. When the umpire and one appraiser sign the same figure, that award settles the amount. If the appraisers can't agree on an umpire, some states let a court or magistrate appoint one.
Does the appraisal clause decide coverage or only the amount of loss?
In most auto policies, the appraisal clause decides only the amount of loss: what the damage costs to repair or what the car was worth. It does not decide whether the loss is covered, who was at fault or whether an exclusion applies. Insurers typically keep the right to deny a claim on coverage grounds even after agreeing to appraisal.
Who pays for the appraisers?
Under the standard wording, you pay your appraiser and the insurer pays its appraiser. Some states change that. Oregon, for example, makes the insurer reimburse your reasonable appraisal costs when the final appraisal beats its last offer. Your policy's appraisal paragraph says how any other costs are shared.